E-COMMERCE: LOYALTY DRIVEN MOBILE PAYMENT PROSPECTS
Practically no one disputes the potential for mobile phones to fundamentally
change the way consumers shop and pay. The real debate is the trajectory at
which this emerging payment type could become ubiquitous. Although both
emerging and developed market consumers are using mobile phones to execute
payments, m-commerce is not projected to be commonplace anytime soon.
Adoption of mobile payment apps will be directly related to the value add that
consumers receive from using mobile phones in lieu of leather wallets. Loyalty
has been shown to be an important factor driving consumer payment choice
before and will be in the mobile payment revolution as well. The loyalty that will
drive mobile payment adoption, however, will be about more than simply points
or miles or free hotel nights. Moving forward, loyalty driven mobile payment
initiatives will be about one-to-one customer engagement and the individual
consumer experience that today’s shopper want and expect.
Loyalty needs to be reimagined

One of the biggest reasons for the slow uptake of mobile wallets has been that
consumers have not yet been given a compelling reason to adopt. An embedded
loyalty scheme could be that reason, but it is important to note that loyalty
is evolving, and moving forward it will be about more than miles and points.
For years, companies thrived by using mass marketing, but such offers have
become less relevant for today’s consumers. It has progressed to the point that
consumers sign up for loyalty programmes they either do not care about or will
never redeem loyalty benefits they have earned.
Mobile wallets have failed to take off in the marketplace due to a combination
of factors, including consumer fears around privacy and security, an
uninformed consumer base, an absence of the needed infrastructure and the
convenience of already established payment methods. Ultimately, mobile
payments must be as cheap, safe and easy to use as traditional payment
methods to even be considered a viable option because consumers will choose
the method of payment that provides the greatest value. In order to encourage
wider adoption and ensure high usage, mobile payment players will have to
provide a value add, which could come in many forms, including monetary
savings, improved security, ease of use or increased loyalty. Of all these
potential benefits, mobile-driven loyalty may be the greatest factor with the
potential to drive consumer adoption of mobile payments.
Although still very much in the early days, the integration of mobile wallets
with value-added services has become almost a prerequisite for the success
of any mobile payment app, especially in more developed markets. One
of the more successful mobile wallets to date comes from the coffeehouse
giant, Starbucks Corp, which integrates its popular rewards program with
its prefunded QR-code based mobile app. In fact, a third of Starbuck’s North
American sales are funded by one of the company’s pre-paid cards, with the
mobile app itself processing 10% of those transactions.
Another real-world example of a loyalty driven mobile payment app is the
telecom-led mobile platform Isis. Although still in the early days of nationwide
deployment in the US, early results have shown greater adoption for those that
signed up for the attached loyalty programmes. It is likely that the payments
industry will see more of these loyalty driven mobile apps in the near future.
Loyalty, which has shown to be an important factor in driving consumer
payment choice in the past when it comes to card payments, will be just as an
important in the mobile revolution. The future consumer adoption of mobile
payments is directly related to this type of value add that consumers receive
from using their mobile phone. Although an embedded loyalty scheme could
provide a compelling reason to try mobile payments, it is important to note
that loyalty as we know it is in need of reinvention. Thanks to the increased
availability of smartphones, the rise of location-based technologies and the
emergence of big data, it is now feasible for companies to deliver a more
personalized loyalty offering than has ever been possible and to do so in real
time. Ultimately, mobile payments will be as much about the exchange of
payments as it is the consumer relationship around the payment transaction.
As the payments landscape continues to evolve and becomes increasingly
more crowded due to the arrival of payment entrants, especially in the mobile
payments segment, it will be that much more important for payment providers
to develop customer-centric offerings that promote loyalty, retention and
ultimately payment spend. Loyalty driven mobile payments products could be
that answer. It’s now more important than ever before for companies to set
themselves apart from competitors. To do so, companies need to have a solid
grasp of where the industry is headed. This is why market research should be a
vital component of any strategic decision.
This white paper contained just a glimpse of the content and analysis available
from Euromonitor International. Information for this white paper was derived
from the report The Mobile Wallet: How Loyalty Could Spur Consumer
Adoption of Mobile Payments, examining the potential for loyalty to drive
mobile payments, which is available on Euromonitor’s website.
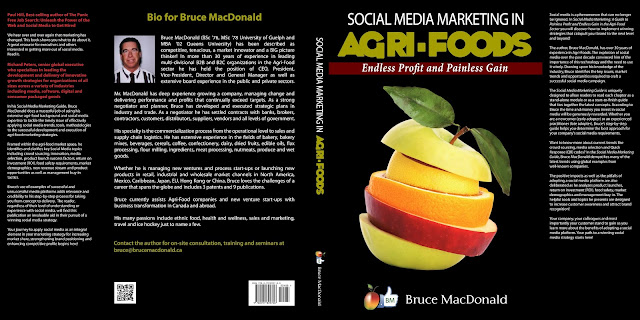
The book is available on Amazon and Kindle for $4.99 USD. Visit amazon/Kindle to order now:
http://www.amazon.ca/Social-Media-Marketing-Agri-Foods-ebook/dp/B00C42OB3E/ref=sr_1_1?s=digital-text&ie=UTF8&qid=1364756966&sr=1-1
Thanks for taking the time
Practically no one disputes the potential for mobile phones to fundamentally
change the way consumers shop and pay. The real debate is the trajectory at
which this emerging payment type could become ubiquitous. Although both
emerging and developed market consumers are using mobile phones to execute
payments, m-commerce is not projected to be commonplace anytime soon.
Adoption of mobile payment apps will be directly related to the value add that
consumers receive from using mobile phones in lieu of leather wallets. Loyalty
has been shown to be an important factor driving consumer payment choice
before and will be in the mobile payment revolution as well. The loyalty that will
drive mobile payment adoption, however, will be about more than simply points
or miles or free hotel nights. Moving forward, loyalty driven mobile payment
initiatives will be about one-to-one customer engagement and the individual
consumer experience that today’s shopper want and expect.
Loyalty needs to be reimagined
One of the biggest reasons for the slow uptake of mobile wallets has been that
consumers have not yet been given a compelling reason to adopt. An embedded
loyalty scheme could be that reason, but it is important to note that loyalty
is evolving, and moving forward it will be about more than miles and points.
For years, companies thrived by using mass marketing, but such offers have
become less relevant for today’s consumers. It has progressed to the point that
consumers sign up for loyalty programmes they either do not care about or will
never redeem loyalty benefits they have earned.
Mobile wallets have failed to take off in the marketplace due to a combination
of factors, including consumer fears around privacy and security, an
uninformed consumer base, an absence of the needed infrastructure and the
convenience of already established payment methods. Ultimately, mobile
payments must be as cheap, safe and easy to use as traditional payment
methods to even be considered a viable option because consumers will choose
the method of payment that provides the greatest value. In order to encourage
wider adoption and ensure high usage, mobile payment players will have to
provide a value add, which could come in many forms, including monetary
savings, improved security, ease of use or increased loyalty. Of all these
potential benefits, mobile-driven loyalty may be the greatest factor with the
potential to drive consumer adoption of mobile payments.
Although still very much in the early days, the integration of mobile wallets
with value-added services has become almost a prerequisite for the success
of any mobile payment app, especially in more developed markets. One
of the more successful mobile wallets to date comes from the coffeehouse
giant, Starbucks Corp, which integrates its popular rewards program with
its prefunded QR-code based mobile app. In fact, a third of Starbuck’s North
American sales are funded by one of the company’s pre-paid cards, with the
mobile app itself processing 10% of those transactions.
Another real-world example of a loyalty driven mobile payment app is the
telecom-led mobile platform Isis. Although still in the early days of nationwide
deployment in the US, early results have shown greater adoption for those that
signed up for the attached loyalty programmes. It is likely that the payments
industry will see more of these loyalty driven mobile apps in the near future.
Loyalty, which has shown to be an important factor in driving consumer
payment choice in the past when it comes to card payments, will be just as an
important in the mobile revolution. The future consumer adoption of mobile
payments is directly related to this type of value add that consumers receive
from using their mobile phone. Although an embedded loyalty scheme could
provide a compelling reason to try mobile payments, it is important to note
that loyalty as we know it is in need of reinvention. Thanks to the increased
availability of smartphones, the rise of location-based technologies and the
emergence of big data, it is now feasible for companies to deliver a more
personalized loyalty offering than has ever been possible and to do so in real
time. Ultimately, mobile payments will be as much about the exchange of
payments as it is the consumer relationship around the payment transaction.
As the payments landscape continues to evolve and becomes increasingly
more crowded due to the arrival of payment entrants, especially in the mobile
payments segment, it will be that much more important for payment providers
to develop customer-centric offerings that promote loyalty, retention and
ultimately payment spend. Loyalty driven mobile payments products could be
that answer. It’s now more important than ever before for companies to set
themselves apart from competitors. To do so, companies need to have a solid
grasp of where the industry is headed. This is why market research should be a
vital component of any strategic decision.
This white paper contained just a glimpse of the content and analysis available
from Euromonitor International. Information for this white paper was derived
from the report The Mobile Wallet: How Loyalty Could Spur Consumer
Adoption of Mobile Payments, examining the potential for loyalty to drive
mobile payments, which is available on Euromonitor’s website.

The book is available on Amazon and Kindle for $4.99 USD. Visit amazon/Kindle to order now:
http://www.amazon.ca/Social-Media-Marketing-Agri-Foods-ebook/dp/B00C42OB3E/ref=sr_1_1?s=digital-text&ie=UTF8&qid=1364756966&sr=1-1
Thanks for taking the time


